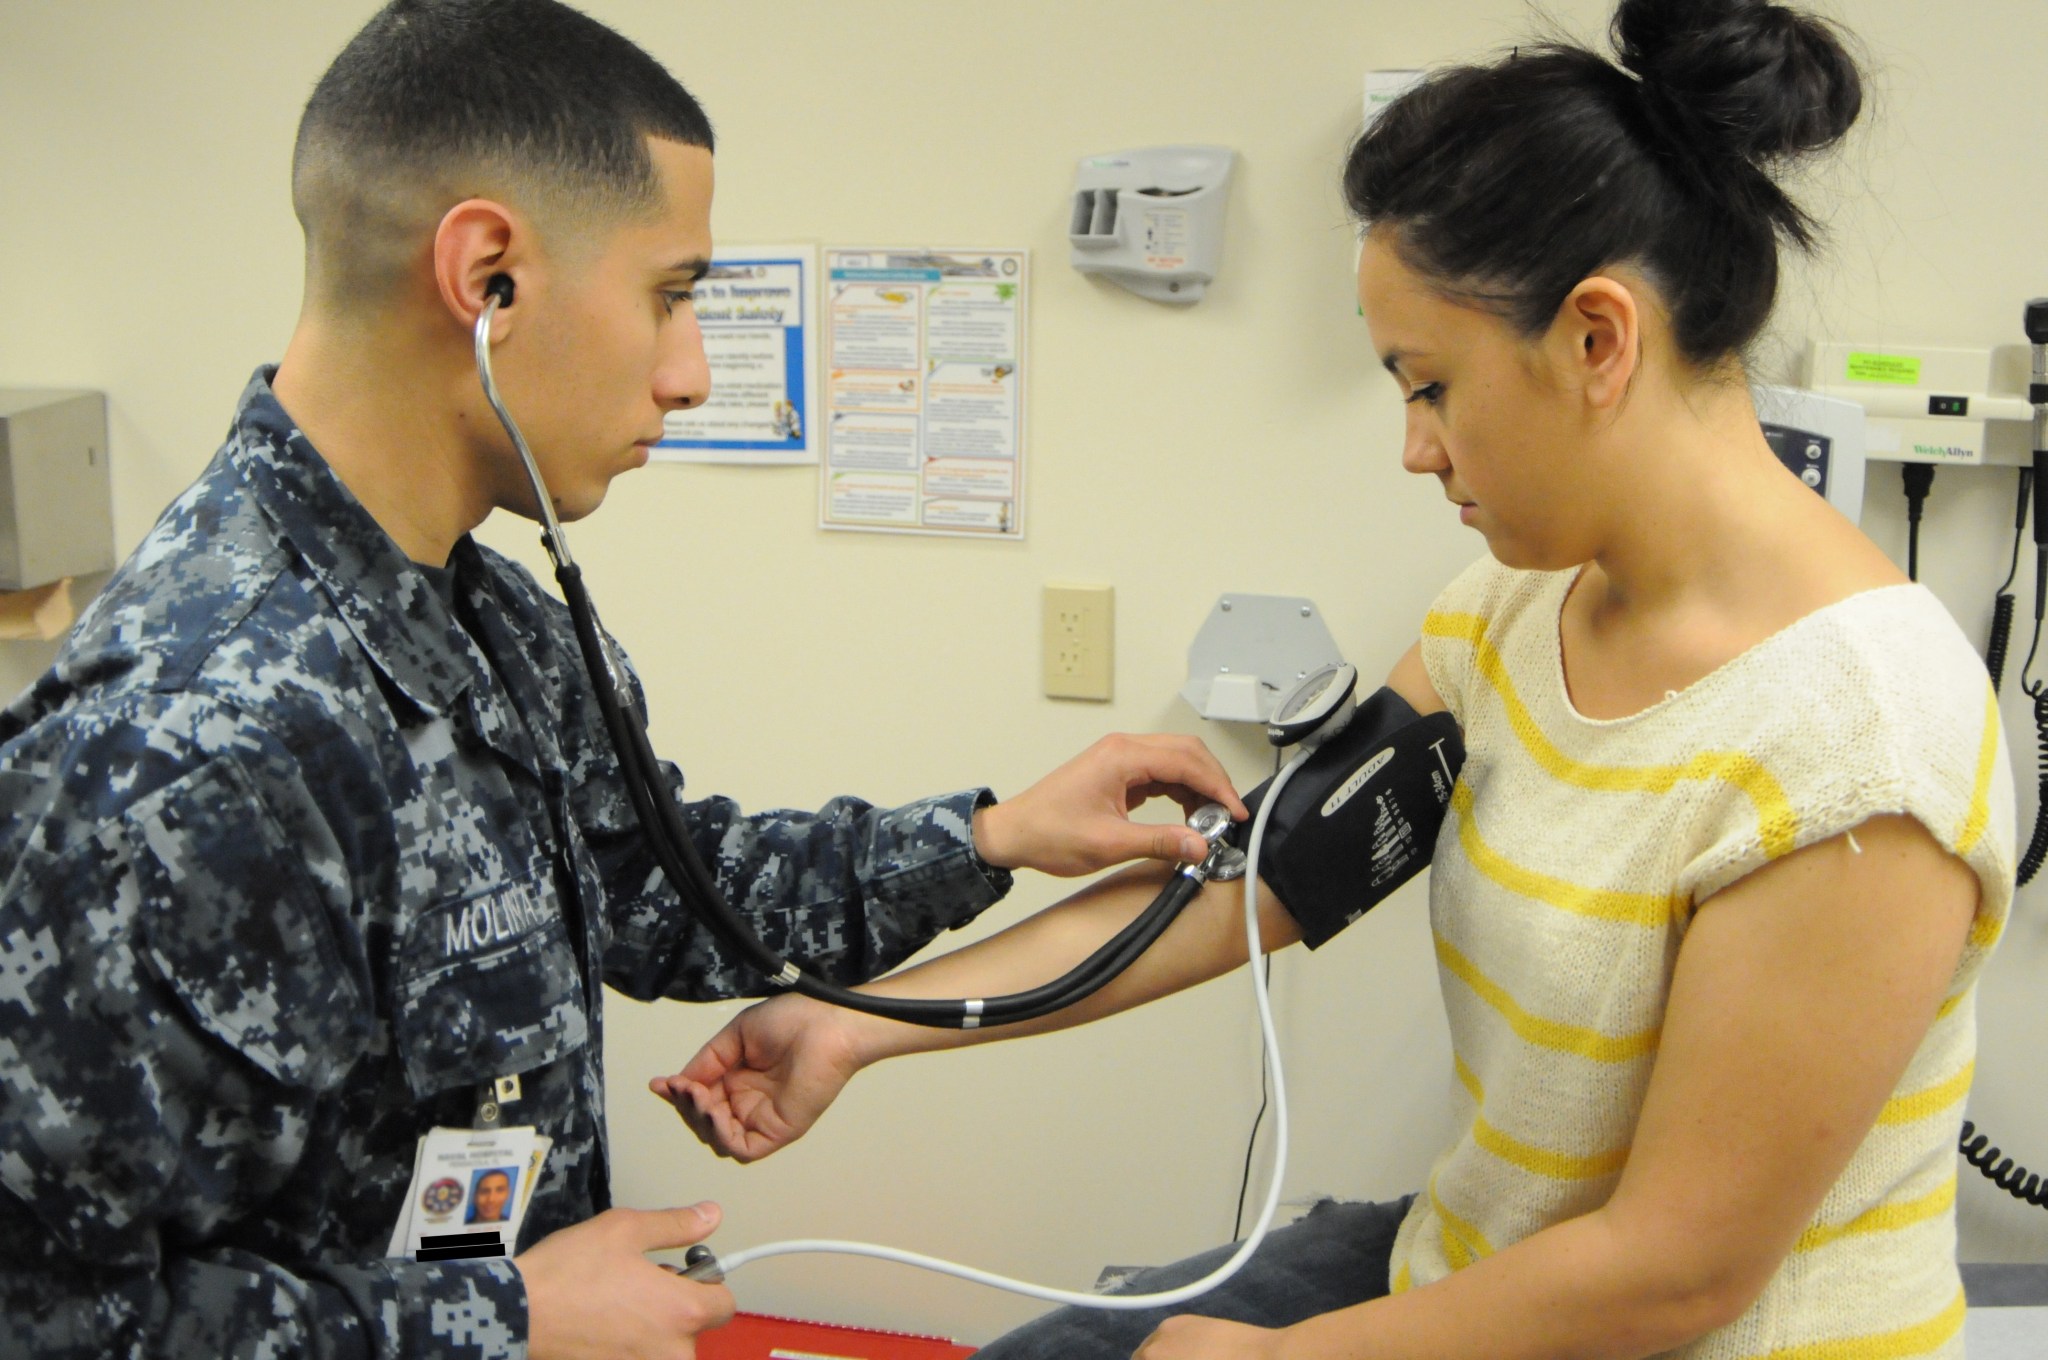
For military families with young adults between the ages of 21 and 26, a familiar budget line item is about to get significantly more expensive. Health insurance premiums for Tricare Young Adult — the coverage program that bridges the gap for military dependents who age out of standard Tricare — are set to climb again in 2027, putting real financial pressure on households that have already sacrificed so much.
The Defense Health Agency has confirmed that beginning January 1, monthly premiums for Tricare Young Adult (TYA) will rise to $893 for TYA Prime and $394 for TYA Select. The changes, which were first reported by Federal News Network, represent increases of 12.5% and 8.5% respectively over 2026 rates. Full details of broader Tricare changes expected in 2027 have not yet been released, but updates to the agency’s operations manual this month confirmed the new premium figures.
Translated into annual costs, military and retiree families with young adult dependents could be looking at between $4,728 and $10,716 in added healthcare expenses each year — on top of what they already pay. By comparison, active-duty families without older children pay nothing in enrollment fees for Tricare Prime and between $50 and $397 per year for Tricare Select, depending on rank and enlistment date. Retiree families pay between $765 and $1,191 per year in enrollment fees. TYA premiums dwarf those figures, and that gap is widening.
A Decade of Steep Increases
The cost of TYA coverage has grown dramatically over the past ten years. A decade ago, TYA Prime enrollees paid $306 a month in premiums, while those in TYA Standard — now called TYA Select — paid $228. Back then, more than 26,900 beneficiaries were enrolled in TYA Prime and over 18,200 in TYA Standard. Since 2016, TYA Prime premiums have jumped 192% and TYA Select premiums have risen 73%.
Today, the situation is nearly reversed. Only about 1,287 people are enrolled in TYA Prime, while approximately 27,600 are enrolled in TYA Select. That shrinking TYA Prime enrollment is a key driver of its skyrocketing costs. When a small group of people is responsible for bearing the full cost of a program — with no government subsidy to offset it — premiums climb fast.
The Defense Health Agency acknowledged this directly:
“A relatively small pool of insured population, combined with a high number of healthcare encounters, result in higher premium rates, particularly for TYA Prime.”
What the Two Plans Actually Cover
TYA Prime functions more like a traditional HMO. Enrollees are assigned a primary care provider — often at a military hospital or contract clinic — and must get referrals before seeing specialists. It comes with no deductibles or copayments, which makes it more predictable but also more expensive in terms of monthly premiums.
TYA Select, on the other hand, gives patients more flexibility. Enrollees can see any physician, including specialists, without needing a referral, and they receive savings for using in-network providers. The tradeoff is a higher deductible and copayments when care is needed.
Why This Program Exists — And Why It Costs So Much
Tricare Young Adult was created in 2011 to give military dependents a coverage option similar to what the Affordable Care Act extended to civilian families — allowing children to stay on a parent’s health plan until age 26. But there’s a critical difference: under federal law, TYA must fully cover its own costs. There is no government contribution to offset what beneficiaries pay. That structure means premiums go up whenever healthcare use increases or enrollment shrinks, with no safety net to soften the blow for families.
For context, the Kaiser Family Foundation reported that the average annual cost of a U.S. family’s employer-provided health plan was $28,303 in 2026 — costs that are largely absorbed by employers, not employees. Military families using TYA get none of that employer-side support.
Families and Advocates Are Sounding the Alarm
The National Military Family Association, an Alexandria, Virginia-based nonprofit that advocates for service members and their dependents, is pushing for answers and for change. The organization says the Defense Health Agency’s explanations don’t “fully explain the underlying factors driving the increases,” and it is working to understand what specific changes in healthcare use or costs are responsible — and why TYA Prime costs are rising faster than TYA Select.
Eileen Huck, director of government relations for the National Military Family Association, warned that rising premiums are creating a dangerous cycle where young adults simply go without coverage.
“It is a vicious cycle because the costs are fully borne by the beneficiary. There’s no government offset. So, as the costs have gone up, young people who either can find less expensive options or feel that they are healthy enough to go without, risk going without health coverage,”
Huck told Military Times in an interview.
TYA is available to unmarried dependents under age 26 of Tricare-eligible sponsors, but only if those young adults don’t have access to employer-offered health insurance and don’t qualify to remain on regular Tricare. Standard Tricare coverage ends at age 21 — or age 23 for full-time college students. That age cutoff itself is a source of frustration.
“It really makes no sense that health coverage is connected to college enrollment,”
Huck said.
“We’ve always been concerned that large numbers of military-connected young adults are going without health coverage because of the cost.”
Legislative Fix Stalled, But Bipartisan Support Grows
Congress has been working since 2021 on legislation that would let military dependents stay on regular Tricare until age 26 — the same benefit civilian families receive through employer plans. The current version of the bill is sponsored by Rep. Patrick Ryan, D-N.Y., in the House and Sen. Mark Kelly, D-Ariz., in the Senate, and has gathered 98 bipartisan co-sponsors.
“We absolutely feel that it’s unfair for military families to have to pay extra for their young adults’ health coverage when … civilian families with employer-based plans get that coverage automatically,”
Huck said.
Short of that legislative fix, the National Military Family Association is pushing for at least one immediate change: allowing all military dependents to remain on Tricare until age 23, regardless of whether they attend college. As Huck put it, a young adult’s access to healthcare shouldn’t hinge on their enrollment status in a university.
Comments are closed.